
== sync, corrected by elderman == @elder man
???; S&P 500: Shares Rise As Earnings Rise
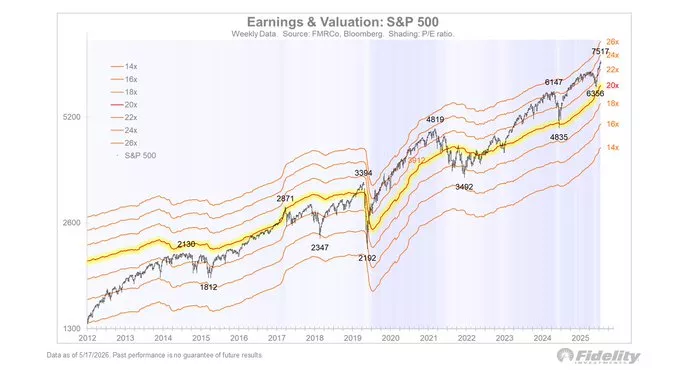
???; Fidelity's chart shows the valuation zones (P/E bands) of S&P 500 based on the estimated profits of the next 12 months. Despite the volatility of recent years, the American market continues to be based on the constant increase in corporate profits, mainly due to AI, technology and strong consumption.
???; According to the analysis, even if the indicator yielded 20 times future profits, S&P 500 could theoretically move close to 6,500 points. However, ever-increasing profitability forecasts operate as «lift» for valuations, limiting possible corrections.
⚠️ The market today seems to be historically accurate, but the big difference from previous cycles is that profits continue to be revised upwards. This keeps the bullish scenario alive, even at an increased risk of short-term corrections.
➡️Black Box Tips:
???; High valuations usually only become viable when accompanied by a strong profit increase
???; The course of interest rates and profitability forecasts will likely determine Wall Street's next major move
???; Up-market corrections often become more shallow when there is strong liquidity and technological growth story
???; Monitoring the predicted P/E helps more than historical P/E in times of rapid profitability change
???????????? Back of the Tablet:
???????? ???? European Shares: Low Expectations, High Risks
???; Only 23% Bank of America's research investors see short-term growth in European shares.
???; on horizon 12 months; the rate goes up to 58%, but both measurements have been at the lowest levels since last April.
???? The Deutsche Bank warns that several investors already have excessive exposure in Europe, therefore the risks cannot be ignored.
???; The war in Iran and oil over 100 bucks press the markets, raise bond yields and strengthen scenarios for 2-3 interest rate increases by the ECB.
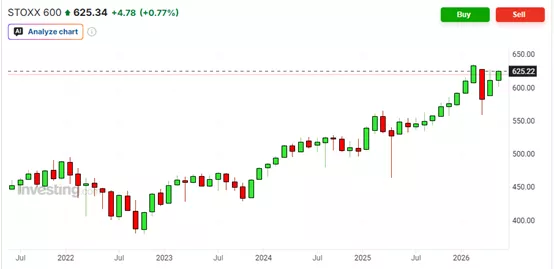
???? The Societe Generale Sees Stoxx 600 on 580 units, the HSBC remains more optimistic with the aim of 670 units.
???; The corporate results in Europe are positive, but lag behind the US, where the Artificial Intelligence It continues to feed profitability.
???; The rise in oil and interest rates can limit the growth margins
???; Energy and consumption sectors remain the main levers for European profits of 2026
???? The CrediaBank remains a special case of transformation, after AMC, HSBC Malta, Pantelakis and now entry into the insurance market via Europe Holdings.
In our Eastern province of the West the week passed was characterized by the climate created by PPC's successful AMC.
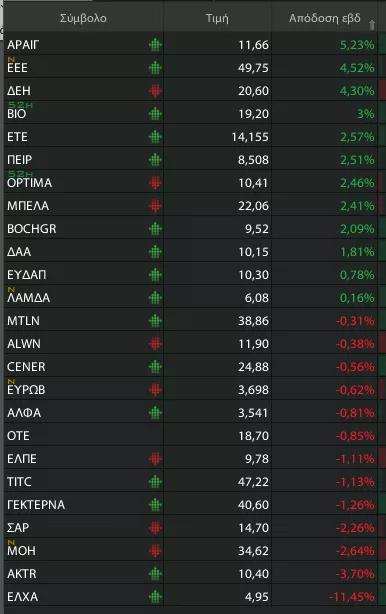
The Credia–Europe Agreement also creates advantages for the Intracom, the BYLOT It gave an upward split with strong turnover.
⚡PPC: On Friday, the share closed with possible due to the registration of profits after the PMC, with attention to the negotiation of new shares in 26/5. ????️ The BIO continues to new high, with performance above +60% from the beginning of the year; and +235% in 12 months.
???? The CENER returned dynamically, closing on high day with +5%.
⚡ THE IPTO closed in historically high with +7,5%, due to the expected PMC and the large investment project. The precedent of PPC's success has paved the way...
???; Intracom–Europe Holdings-Credia:
???? The Intracom exits the deal with significant benefit, As the net value of Europe Holdings' transaction with Credia Bank is estimated to be close to EUR 60 million.
???? The project nearly doubled its value in a year, justifying those involved in the May 2025 capital increase and believing in time in Europe Holdings' strategy.
???; Refund of EUR 45,5 million, or EUR 0,31 per share, acts as an additional «dowry» for shareholders prior to completion of the agreement.
???; Credia Bank acquires insurance with an extremely strong solvency index 366%, an element that enhances her profile in the Bancassurance area.
???; Maintaining the administrative team shows that buyers buy not only assets, but also know-how, network and executive capacity.
???; For the investor, the deal shows that hidden goodwill in entries can be unlocked quickly when there is proper timing
???? The Intracom strengthens its investment account as a group that creates value through targeted participations
???; Bancassurance now becomes a key growth lever for Credia Bank and can offer repeated higher quality revenue
➡️ Black Box Tips:
???? The investor sees market without general momentum, but with strong selective movements
???? The CrediaBank, The PPC, The IPTO and the group BIO the key monitoring points remain
???; Wall Street holiday Monday can keep the market at a more careful pace
???; PPC: The New Age Caban
⚡ PPC comes to the forefront of the Greek capital market with strong symbolism. The bell on Euronext Athens by George Stassis is not just a ritual move, but a signal of transition to a new investment phase.
The increase in capital EUR 4,25 billion, with bids above EUR 18 billion, confirms the strong trust of international institutional and large investment funds in the company's strategy.
???; The expected capitalization near EUR 11.5 billion now places PPC in the top listed market, in complete contrast to the image of a weakness of previous years.
⚫ Black Box Assessment: PPC changes track
⚡ PPC's image today reminds more of European energy growth story than traditional state-owned utility company. The over-covering of the PMC and the quality of investors show that large international portfolios «buy» Not only today's figures, but above all the role the company can play in the energy transition of Southeast Europe.
???; The market seems to discount that new funds will accelerate growth in RES, storage and networks, sectors offering higher valuations and more stable cash flows. At the same time, the inclusion of strong foreign funds increases the international visibility of the stock and possibly opens the way for greater participation in European indicators.
⚠️ However, the higher the valuation, the higher the market requirements. Investors will now expect quick implementation of projects, strong profitability and cost discipline.
➡️Black Box Tips:
???? The point is to carry out the investment plan without excess costs.
???; CrediaBank: In 2026 it begins with historical performance
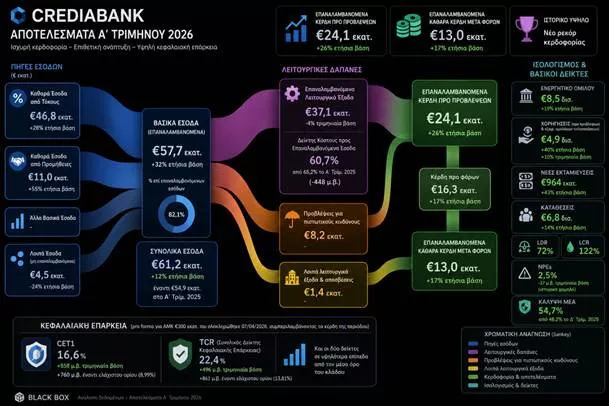
???; CrediaBank shows that the 2026 strategy yields, as the first quarter recorded historically high performance in profitability, financing and credit expansion.
???; Recurrence gains before provisions The Commission has therefore decided to grant aid to the steel industry. €24.1 million, increased by 26%, In addition, the net earnings formed in €13 million; with rise 17%.
???; The new disbursements They've arrived. €ECU 964 million.,noting an increase 43%, with a base lever Small and medium-sized enterprises and complex financing.
???; The net credit extension almost doubled in €459 million, confirming that the bank earns shares in a competitive industry.
The lending portfolio ejected to €4.9 billion, with increase 40%, i.e. at a rate of about five times higher from the banking sector.
????️ Deposits It's over. €6.8 billion, increased by 14%, maintaining strong liquidity and supporting the next development phase.
➡️ Black Box assessment:
⚡ CrediaBank's image reminds more of a bank in transition growth than of traditional small and medium-sized Greek banks. The growth rates of loans, supplies and assets show that the administration is attempting aggressive expansion before the new banking cycle in Greece matures fully.
???? The most positive element is that growth is not at the expense of quality assets. On the contrary, the NPE at 2.5% is extremely low for a bank that runs almost twice the market. This shows that so far the grants are made with relative discipline.
???; The large capital increase changes the bank level. With CET1 at 16.6%, CrediaBank acquires a strong pillow to fund acquisitions, development in Malta and digital transformation without immediate need of new funds. The market usually rewards such banks when it is shown that they can turn growth into sustainable profitability.
???? The big bet now is HSBC Malta. If integration succeeds without operational problems and without pressure on loan quality, CrediaBank can become a regional banking player with a much higher valuation than today. But if there are delays or increased integration costs, the market will probably become more cautious.
➡️ Black Box Tips:
???; The market will likely continue to monitor whether high credit growth can be maintained without a risk increase.
???; HSBC Malta's integration will be a key execution test for management over the next quarters.
???; Strengthening commission revenue can function as a catalyst for higher valuations in the future.
???; Strong capital adequacy creates room for new acquisitions and more aggressive expansion.
⚡ IPTO: Capital increase opens the way for network 6 billion euros
???? IPTO enters a new investment cycle, with a plan EUR 6 billion by 2029 and focusing on electrical connections that change the country's energy map. The book building a capital increase of EUR 1 billion is expected at the end of June, with the participation of the State, which strengthens market confidence.
????️ Links Dodecanese and North Aegean are key projects, as they reduce the dependence of islands on accurate units and open up space for more RES.
The international dimension, with the GRITA 2 and possible connections with Turkey and Albania, strengthens the role of Greece as an energy portal.
⚫ Black Box Assessment:
⚡ IPTO appears to be converted from a classic network manager to one of Southeast Europe's most important energy investment players.
???; The market focuses mainly on its overfolding Adjustable Asset Base (RAB)), as this creates visibility in revenue and cash flows for many years. In an environment of increased demand for electricity and expansion of RES, IPTO acquires "compounder" features for long-term capital.
At the same time, international connections can give the country geopolitical goodwill and strengthen the strategic importance of the group.
➡️Black Box Tips:
???? The reader sees IPTO as adjustable development story
???? The main bet is the successful execution of projects
The increase in RAB is the core of future profitability
???; Sun: The "Invisible" First Matter to Move the Technological Revolution
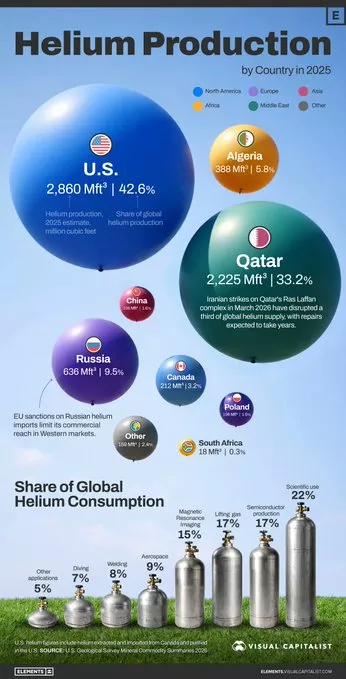
???; The sun evolves into one of the most strategic raw materials of the new era, as without it critical industries such as semiconductors, magnetic scanners, aerospace and artificial intelligence applications cannot function. The picture of world production clearly shows how concentrated the market is, with the US and Qatar controlling nearly 76% of total production.
⚠️ The problem is that the sun market doesn't function as a normal commodity market. Infrastructure is extremely specialized, transport difficult and alternatives limited. The sanctions in Russia and the crisis in Qatar after Iranian blows revealed how fragile the global supply chain is.
???; Increasing demand from AI data centers, chips and medical technology will probably lead to new geopolitical value for the sun, equivalent to that with LNG or rare earths. Anyone who controls critical raw materials of the future acquires technological and industrial power.
???; AS Company: Durable growth with emphasis on own branded products
AS Company started in 2026 with a positive sign, recording a sales increase against 10,48% and EBITDA aid against 21,5%, development which shows that the strategy for strengthening own branded products is starting to work effectively. The EBITDA margin in 20,56% is considered particularly strong for the gaming and lifestyle industry, confirming better cost control and higher returns per product.
???; The increased participation of own branded products, already close to 40% sales, acts as a key lever for improving profitability and diversification from competition. At the same time, the categories Baby and Kidult/lifestyle create prospects for greater resilience to the variability of the game market.
➡️ Black Box assessment:
AS Company appears to be going through a more mature growth phase, where the main issue is not only increasing sales but mainly strengthening profitability and margins. The rise of EBITDA against 21,5% and maintaining a high margin of over 20% is a strong indication that the shift strategy towards own branded products delivers.
???; If the company manages in the next few years to increase the participation of the own branded near 50%, then it can see even greater improvement in gross margin, better cash flow and higher market valuation. At the same time, the categories Kidult, lifestyle and baby create access to audiences with greater consumer resistance and better profit margins.
???; The great challenge remains the international supply chain, as increased transport costs and geopolitical tensions can push margins. In addition, the company remains fairly dependent on the course of consumption and seasonality.
???; Nevertheless, strong liquidity, low leverage and stable dividend policy create an image of a defensive small and medium-sized company with the ability to gradually upgrade its valuation over the coming years.
➡️Black Box Tips:
???; Improving margins shows quality growth rather than just increasing sales
???; Own branded products usually offer higher profitability and higher price control
???; Easter seasonality probably carries part of the demand to the second quarter as well.
???; Mining policy acts as important «pillow» in periods of variability
????⚡ China «Electrodes» Africa and Builds Geopolitical Empire
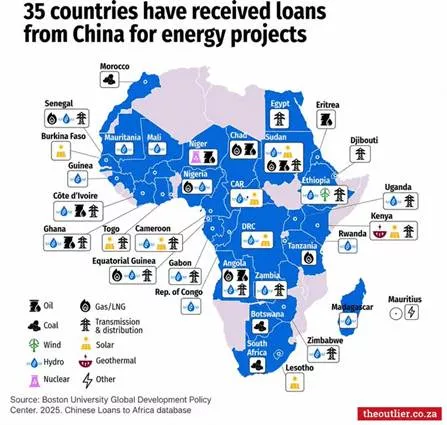
???; China is gradually turning into Africa's largest energy financier, creating a new geo-economic network of influence across the continent. According to the data, 35 African countries have received Chinese loans for energy projects, from oil and gas to hydroelectric, transport and renewable sources.
⚡ The Beijing strategy is not only limited to securing raw materials. China «build» energy infrastructure, gaining long-term political and economic influence in areas with enormous development needs. At the same time, many African economies are increasingly dependent on Chinese funding and technology.
????️ They distinguish oil and LNG projects in Nigeria, Angola and Sudan, while hydroelectric and transport networks dominate Central and Eastern Africa.
???; The picture shows that the energy battle of the future concerns not only energy production, but also the control of infrastructure, loans and geopolitical influence.
⚛️ Οι ΗΠΑ επενδύουν δισεκατομμύρια στους κβαντικούς υπολογιστές
???? Η αμερικανική κυβέρνηση σχεδιάζει επενδύσεις ύψους 2 δισ. δολαρίων στον κλάδο των κβαντικών υπολογιστών, αποκτώντας συμμετοχές σε εννέα εταιρείες στρατηγικής σημασίας, μεταξύ των οποίων η IBM και η GlobalFoundries.
???????? Ο βασικός στόχος είναι η ενίσχυση της εγχώριας παραγωγής, η θωράκιση των εφοδιαστικών αλυσίδων και η μείωση της εξάρτησης από την Κίνα σε κρίσιμες τεχνολογίες.
???? Η IBM αναμένεται να λάβει περίπου $1 billion, ενώ η GlobalFoundries περίπου 375 εκατ. δολάρια. Στο πρόγραμμα συμμετέχουν επίσης οι D-Wave Quantum, PsiQuantum, Rigetti Computing και άλλες νεοφυείς εταιρείες του κλάδου.
⚠️ Παρά τον ενθουσιασμό, η εμπορική αξιοποίηση της τεχνολογίας παραμένει μακρινή. Ο CEO της Nvidia, Jensen Huang, εκτιμά ότι πραγματικά χρήσιμοι κβαντικοί υπολογιστές ίσως αργήσουν ακόμη δύο δεκαετίες.
➡️ Black Box Tips:
???? Οι κβαντικοί υπολογιστές αποτελούν περισσότερο ένα μακροπρόθεσμο γεωπολιτικό και τεχνολογικό στοίχημα παρά μια άμεση επενδυτική ευκαιρία
???? Η κρατική στήριξη δείχνει ότι οι ΗΠΑ αντιμετωπίζουν πλέον την τεχνολογία ως θέμα εθνικής ασφάλειας
???? Οι επενδυτές χρειάζεται να διαχωρίζουν τον ενθουσιασμό της αγοράς από τον πραγματικό χρονικό ορίζοντα εμπορικής αξιοποίησης
⚡???? «Έξυπνοι» Μετρητές: Η ψηφιακή επανάσταση του ΔΕΔΔΗΕ στην Αττική
⚡ Ο ΔΕΔΔΗΕ επιταχύνει την ενεργειακή μετάβαση της χώρας, προχωρώντας δυναμικά στην εγκατάσταση «έξυπνων» μετρητών ηλεκτρικής ενέργειας, με την Αττική να βρίσκεται στο επίκεντρο του σχεδιασμού. Το έργο, ύψους περίπου 1,16 δισ. ευρώ, θεωρείται από τα σημαντικότερα βήματα εκσυγχρονισμού του ελληνικού δικτύου διανομής ηλεκτρικής ενέργειας.
???? Ήδη έχουν εγκατασταθεί πάνω από 1,5 εκατ. ψηφιακοί μετρητές, ενώ ο στόχος φτάνει τα 2,2 εκατ. έως το τέλος του 2026. Οι νέες συσκευές επιτρέπουν αυτόματη καταγραφή καταναλώσεων, απομακρυσμένες συνδέσεις και διακοπές παροχών, μειώνοντας λειτουργικά κόστη και βελτιώνοντας την αποδοτικότητα του δικτύου.
????️ Παράλληλα, οι καταναλωτές αποκτούν σχεδόν σε πραγματικό χρόνο εικόνα της ενεργειακής τους συμπεριφοράς, γεγονός που μπορεί να ενισχύσει την εξοικονόμηση ενέργειας και να ανοίξει τον δρόμο για πιο ευέλικτα και προσωποποιημένα τιμολόγια.
???? Κρίσιμο ρόλο θα διαδραματίσει και το σύστημα Meter Data Management, το οποίο θα επεξεργάζεται τεράστιο όγκο δεδομένων κατανάλωσης, δημιουργώντας τις βάσεις για ένα πιο «έξυπνο», διαφανές και τεχνολογικά αναβαθμισμένο ενεργειακό σύστημα.
⚙️???????? Η Bosch σηματοδοτεί το τέλος μιας εποχής στη γερμανική βιομηχανία
???? Η απόφαση της Bosch να καταργήσει έως το 2030 περίπου 22.000 θέσεις εργασίας στη Γερμανία δεν μοιάζει με ένα απλό πρόγραμμα περικοπών. Πρόκειται για μια βαθιά στρατηγική αναδίπλωση ενός από τους ιστορικότερους βιομηχανικούς πυλώνες της Ευρώπης, καθώς η μετάβαση από τους κινητήρες εσωτερικής καύσης στην ηλεκτροκίνηση αλλάζει βίαια τις ισορροπίες.
???? Η Βάδεν-Βυρτεμβέργη, η παραδοσιακή «καρδιά» της αυτοκινητοβιομηχανίας, βρίσκεται στο επίκεντρο των πιέσεων. Μόνο στην περιοχή της Στουτγκάρδης περίπου 240.000 θέσεις εργασίας εξαρτώνται άμεσα ή έμμεσα από τον κλάδο του αυτοκινήτου, ενώ οι προμηθευτές κινδυνεύουν με επιπλέον 90.000 έως 100.000 απώλειες θέσεων εργασίας τα επόμενα χρόνια.
⚡ Το μεγαλύτερο πρόβλημα δεν είναι μόνο η ηλεκτροκίνηση, αλλά το γεγονός ότι οι νέες επενδύσεις σε software, μπαταρίες και τεχνολογία κατευθύνονται ολοένα και περισσότερο εκτός Γερμανίας, λόγω υψηλού ενεργειακού κόστους, φορολογικής πίεσης και αυξημένης γραφειοκρατίας.
???? Η Bosch ουσιαστικά εκπέμπει ένα ηχηρό μήνυμα: η ευρωπαϊκή βιομηχανική υπεροχή δεν θεωρείται πλέον δεδομένη. Και αυτό ίσως αποτελεί την πιο σοβαρή προειδοποίηση για τη μελλοντική ανταγωνιστικότητα της γερμανικής οικονομίας.
????????️ Επιστολές αναγνωστών
Αύξηση Μετοχικού Κεφαλαίου ΑΔΜΗΕ
Καλησπέρα σας κ. Στούπα,
Παρακολουθώ την αρθρογραφία σας καθημερινά και συμφωνούμε σε πολλά από αυτά που γράφεται.
Είμαι ένας μικροεπενδυτής στο ΧΑΑ όπου κατέχω 200 μετοχές της ΑΔΜΗΕ Συμμετοχών Α.Ε.
Σχετικά με την ΑΜΚ του ΑΔΜΗΕ διαβάζω ότι η ΑΔΜΗΕ Α.Ε. που δεν είναι εισηγμένη θα προχωρήσει σε ΑΜΚ με τιμή μετοχής για τις νέες μετοχές 1 ευρώ/μετοχή.
Η ΑΔΜΗΕ Συμμετοχών θα χρειαστεί να συνεισφέρει το 51% του 1 δις που χρειάζεται η ΑΔΜΗΕ Α.Ε.
Αυτό σημαίνει πως η ΑΜΚ της ΑΔΜΗΕ συμμετοχών που είναι η εισηγμένη εταιρεία θα είναι σε αυτή τη τιμή, του ενός ευρώ ανά μετοχή;
Για αυτό και το ράλι της μετοχής το τελευταίο διάστημα;
Ευχαριστώ πολύ για το χρόνο σας.
Σε περίπτωση δημοσίευσης παρακαλώ μόνο τα αρχικά μου.
Α.Π.
Kind regards,
Απάντηση: Καλησπέρα σας κ. Π.,
ευχαριστώ για τα καλά σας λόγια.
Από όσο γνωρίζουμε μέχρι στιγμής, η αύξηση κεφαλαίου αφορά την μη εισηγμένη ΑΔΜΗΕ Α.Ε. και όχι απευθείας την εισηγμένη ΑΔΜΗΕ Συμμετοχών.
Η τιμή του 1 ευρώ ανά μετοχή που αναφέρετε αφορά την ονομαστική αξία ή την εσωτερική αποτίμηση της μη εισηγμένης εταιρείας στο πλαίσιο της διαδικασίας και όχι την τιμή στην οποία θα μπορούσε να γίνει τυχόν ΑΜΚ της εισηγμένης.
Συνήθως σε τέτοιες περιπτώσεις η τιμή διάθεσης τοποθετείται με έκπτωση σε σχέση με την αγορά, αλλά όχι σε επίπεδα που θα προκαλούσαν ακραία απομείωση της αξίας των παλαιών μετόχων.
Η ΑΜΚ της εισηγμένης θα είναι για 530 εκατ. προκειμένου να καλύψει τη συμμετοχή της στην ΑΜΚ της ΑΔΜΗΕ.
Το πρόσφατο ράλι της μετοχής πιθανότατα συνδέεται περισσότερο με:
- Το ενδιαφέρον που προκάλεσε η ζήτηση για την πρόσφατη ΑΜΚ της ΔΕΗ.
τις μεγάλες επενδύσεις διασυνδέσεων,
την αναβάθμιση του ενεργειακού ρόλου της χώρας,
τις προοπτικές αυξημένων ρυθμιζόμενων εσόδων,
αλλά και την προσδοκία συμμετοχής ισχυρών θεσμικών επενδυτών στο νέο επενδυτικό κύμα.
Βέβαια, όσο πλησιάζουν οι τελικές ανακοινώσεις για τη δομή χρηματοδότησης, η αγορά θα αρχίσει να τιμολογεί πιο συγκεκριμένα και τον πιθανό βαθμό dilution για τους υφιστάμενους μετόχους.
*Αποποίηση Ευθύνης: Το υλικό αυτό παρέχεται για πληροφοριακούς και μόνο σκοπούς. Σε καμιά περίπτωση δεν πρέπει να εκληφθεί ως προσφορά, συμβουλή ή προτροπή για την αγορά ή πώληση των αναφερόμενων προϊόντων. Παρόλο που οι πληροφορίες που περιέχονται βασίζονται σε πηγές που θεωρούνται αξιόπιστες, ουδεμία διασφάλιση δίνεται ότι είναι πλήρεις ή ακριβείς και δε θα πρέπει να εκλαμβάνονται ως τέτοιες.

