
LAST INFORMATION 14:00
of Manos Hachladakis
Constantly uphill with a widespread market interest in high capitalization, Athens Avenue moves, utilizing the improved mood internationally after the new US sanctions in Iran did not seem to scare the investment community.
In particular, the General Index negotiates at 2,655 units with +0.9% and the turnover at 110m euros but at 27m in 13 packages, and 17m pieces have been moved.
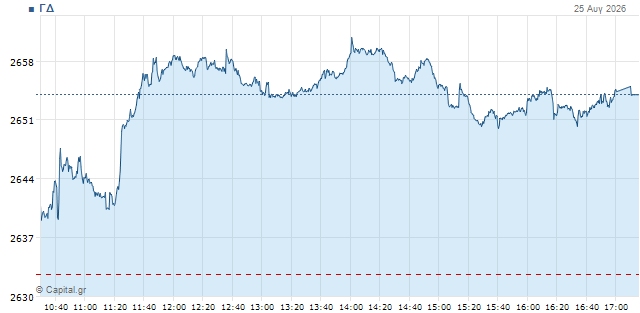
The banking index is increased by 1.35% to 3.11 units and the high capitalization FTSE moves at 6,794 mon. with +1%, while the mid-term FTSEM stays behind remaining with no substantial change at 3.097 μm.
On the positive side of the day, the upward movement is also accompanied by increased trade activity yesterday, after a rather procedural meeting, with the turnover at EUR 177 million. and the DG recording a change of just 0.08%, although overall the turnover remains low today.
At international level, climate positive seems to have affected the fact that the American campaign "economic D-Day" against Iran, as President Trump, who was presented yesterday, is found to be milder than expected, as he had the threat of ousting from the dollar system for those countries that have transactions with Tehran, but without specifying who they are or any timetable for imposing sanctions.
However, in the wider picture of the last period, both within and outside borders, investors show a waiting attitude and not taking initiatives in a clear direction, possibly in view of the planned events of the week that have the potential to change the landscape greatly.
In particular, tomorrow after the closure of Wall Street another verdict is expected on the broader prospects of the artificial intelligence ecosystem with the results announced by the industry's flag company (and more generally global markets now) Nvidia, while the technological sector seems to be under some pressure again, while two days later Kevin Wars will need to refer indirectly or directly to the outlook of Fed's interest rates in his first speech at Jackson Hall's symposium as head of the federal bank.
Accordingly, in Athens, apart from the small changes in the last period (at the last 12 meetings the 10 had closed with a change of less than 0.5%), the steadily declining trading activity (last night 177.56m euros, Friday 194.1m and Thursday 200.2m) shows liquidity that "stays on the bench", with portfolios that probably await a more appropriate time to be placed. An example was that on the dashboard yesterday it was less than EUR 147 million (and another EUR 30.8 million in packages, one worth EUR 15.8 million in Metlen).
Moves on the dashboard
Today, however, the movements of investors are more clear and have been consistently affected by higher valuations since the morning, with the banking sector returning to dynamic rates.
EIB, Piraeus and Alpha all about +1,4% and Eurobank at +0,8%.
Even better the DTP's cubs move. Credia at +3.3% after +3.1% yesterday, Optima also with a 2.6% jump, while Cyprus is being strengthened more gently by 1.1%.
At the top of the 25th moves Cenergy which produces an upward reaction of more than 4% after a six-day drop.
PPC is also moving 23 euros with profits above 3.8%.
AKTOR, Allwyn, GEK TERNA, Titan, Biocoal and ELHA also operate in the other options of buyers in high capitalization.
Metlen remains at EUR 48.86 with a turnover of 18.5 million due to two packages of 320 thousand pieces worth a total of 15.6 million, one 153 thousand shares at EUR 48.78 and the other for 167 thousand at 48.8.
Pressures are mainly received by the refineries, Helleniq Energy at -2,6% and Motor Oil at -1.5% in view of its semester announcement this afternoon.
In mid caps IPTO, PPA and Avax all are reinforced about 0.8%, while Intralot retreats by 0.9% and Qualco by 1%.
Over the entire table 68 shares move upwards against 58 pitches.
The image internationally
Oil expands prices, as investors assess the new US economic sanctions in Iran.
Brent at $89.6 a barrel with minus 2.7% and American WTI at $82.5 with a minus 2.9%.
Accordingly, European gas is falling to EUR 66.5 per megawatt hour with -2.5 per cent.
In the shares, the contracts of the American indices move up in a purely upwards time, after a meeting with losses for both of the three yesterday (S&P 500–0.3%, Nasdaq–0.7%).
Dow Jones' futures at +0.4%, S&P 500 at +0.45% and Nasdaq at +0.9%.
Similarly, in Europe, indicators are consistently positive and raise rates, since yesterday Stoxx 600 closed completely unchanged (0%).
German DAX at +0.75%, French CAC 40 at +0.4%, British FTSE 100 at +0.2%, Italian FTSE MIB +0.65%, Spanish IBEX 35 at +0.3% and the pan-European high capitalization of Stoxx 50 at +0.5%.
In the bond market returns have changed direction and move to lower levels as losses widen into the slow. The ten-year US at 4.66%, the German title at 3.22% and the French at 4.07%, with the Greek at 3.88%.
Finally, in metals gold remains around the high three months around $4,700 an ounce and silver yields to $67.8 with -1%.

