
Interesting and contradictory developments in the housing market record its new quarterly bulletin IOBE and Cepal for private debt to the Greek economy. According to the special chapter «The profile of the extension of the housing supply in Athens and Thessaloniki, 2025–2026», there are three seemingly counterbalanced trends. Prices continue to increase, sales notices multiply and recorded sales decline. The data come from official sources (ELSTAT, TTE) and from the processing, by ReDataset, of sales orders on digital platforms and data on the Real Estate Transfers Registry.
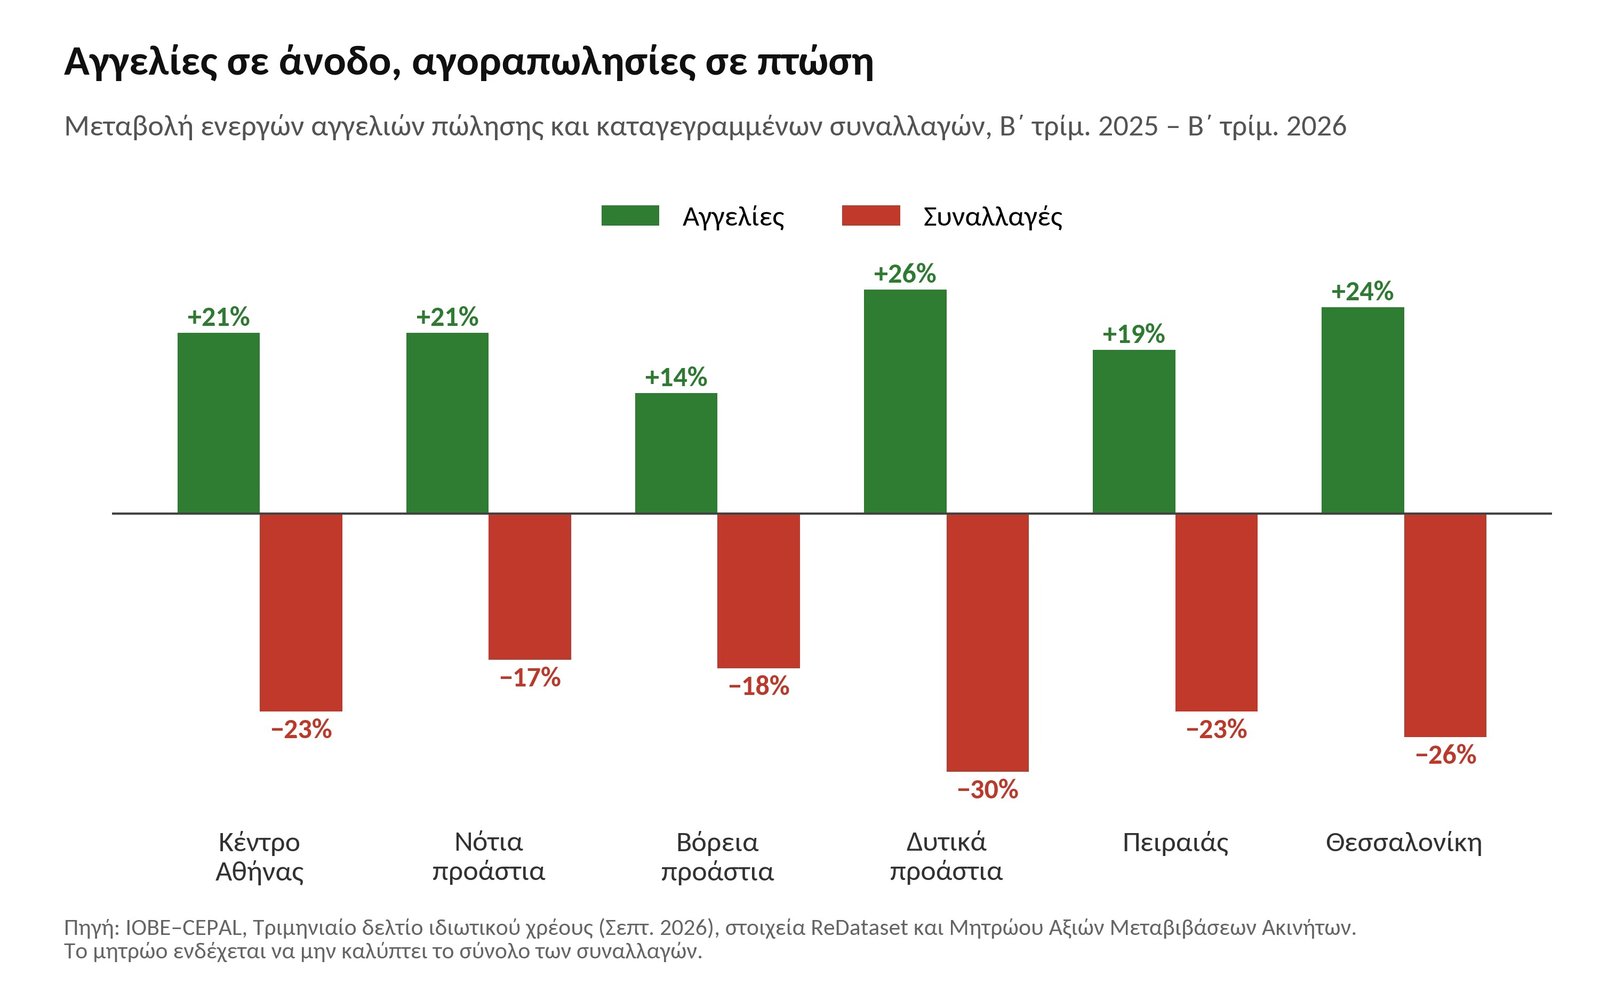
Between the second quarter of 2025 and the second quarter of 2026, housing sales notices in capital and co-capital increased by 15% to 26% and stayed longer in «digital shelf», while recorded transactions decreased by 17% to 30%. Prices, however, continued to rise, with Thessaloniki leading. THE TTE housing price index It increased in the first quarter of 2026 by 5.8% annually throughout the country, by 6.2% in Thessaloniki and 2.5% in Athens.
source: IOBE-Cepal, treatment: Claude
Why don't the prices drop?
These findings do not confirm, at least for the time being, the pattern that yields price changes exclusively to the supply and demand balance. In theory, more houses for sale and fewer purchases should be pushing prices downward. However, the image is more complex. The fewer transactions do not necessarily mean less demand, since mortgage disbursements more than doubled, reaching 1.14 billion euros in the second quarter of 2026 from 492 million euros a year earlier. In addition, the price index relates to the first quarter, so a possible effect of the slowdown may be seen later.
If the pressures on the housing market are reflected somewhere, they are on the split between the requested and the final price. In the southern suburbs of Athens, one of the country's most expensive markets, the final price is estimated on average 38.5% lower than the requested, the largest deviation between the six regions. According to the bulletin, the difference suggests a greater margin of negotiation between a seller and a buyer. The smallest split is recorded by Thessaloniki and the northern suburbs.

Empty dwellings
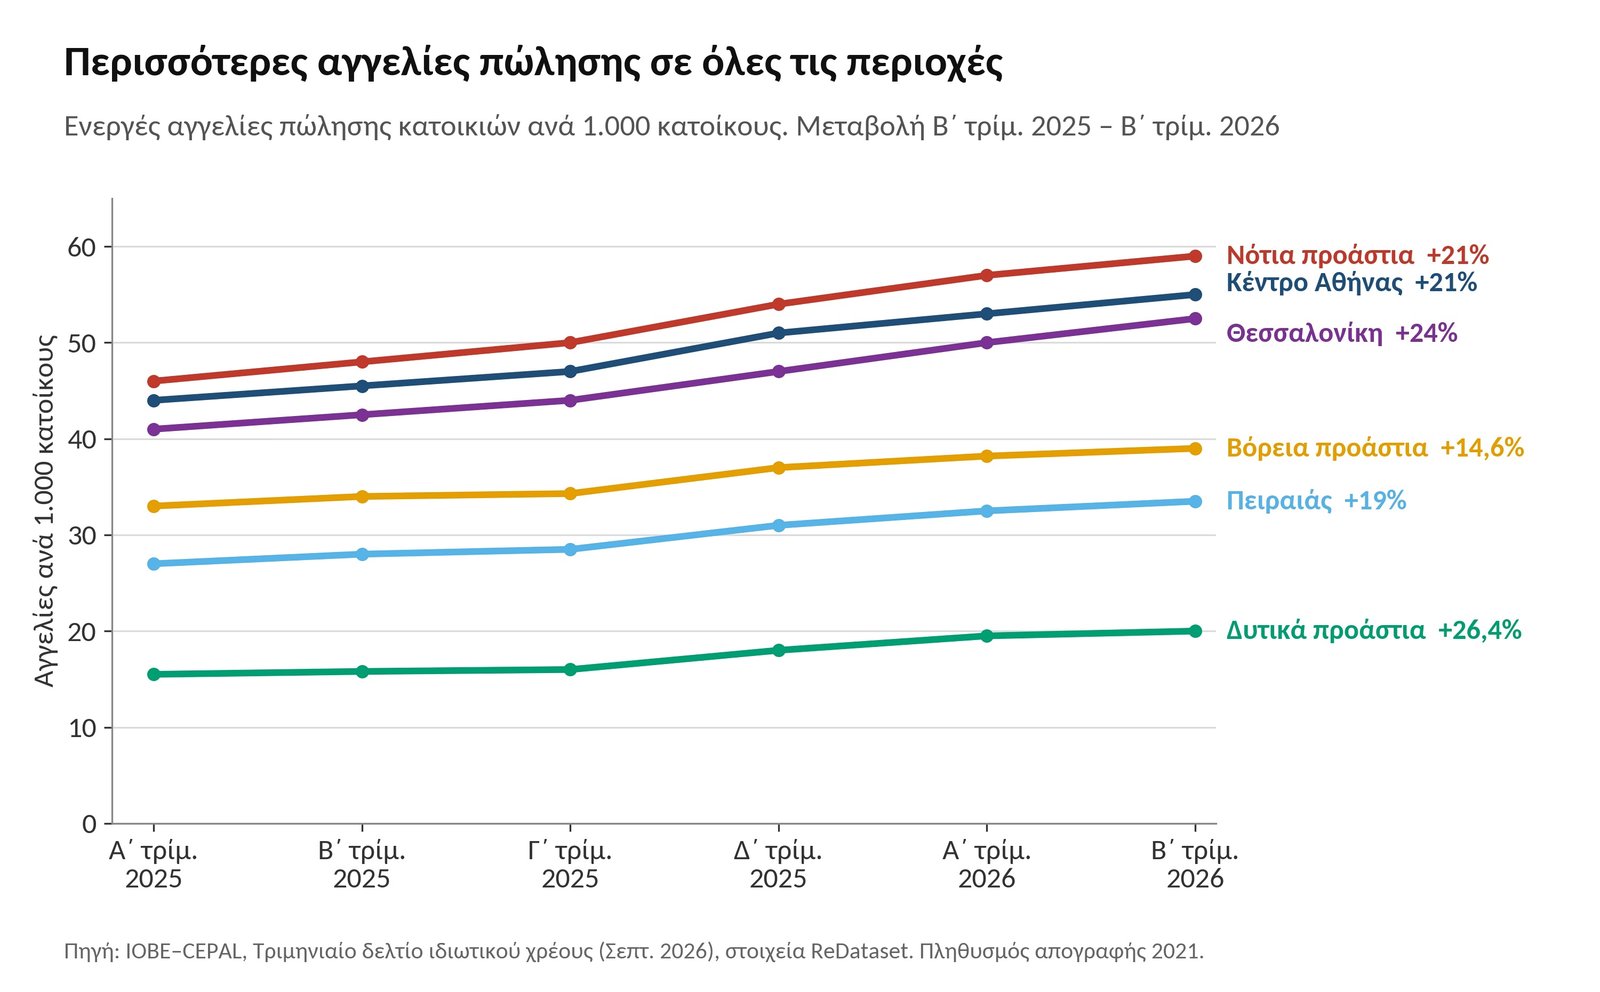
Active sales announcements per 1,000 inhabitants increased in all six areas examined by the study. The smaller rise was recorded in the northern suburbs (+14.6%) and the largest in the west (+26.4%), with Thessaloniki following by foot (+24%). In the centre of Athens and the southern suburbs the increase was 21% and in Piraeus 19%. The densest offer in relation to the population gather the southern suburbs, the centre of Athens and Thessaloniki. It is no coincidence that the areas with most ads are also those with the largest reserve of empty dwellings. According to the 2021 census, 24.1% of the houses in central Athens and 23.5% in Thessaloniki were vacant, compared to 13.9% in the northern suburbs.
Greater supply, lower absorption
The housing market had difficulty absorbing the additional offer. The largest drop in trades recorded the western suburbs of Athens, areas that until recently were considered affordable, where purchases decreased by 30% when ads increased by 26%. Here are Thessaloniki (−26%) and, in third place, the center of Athens and Piraeus (−23%). The southern and northern suburbs are more resistant, with a decrease in trade by 17% and 18% respectively. The bulletin states that the trade register does not cover all sales, but the trend is clear.
More time to sell a house
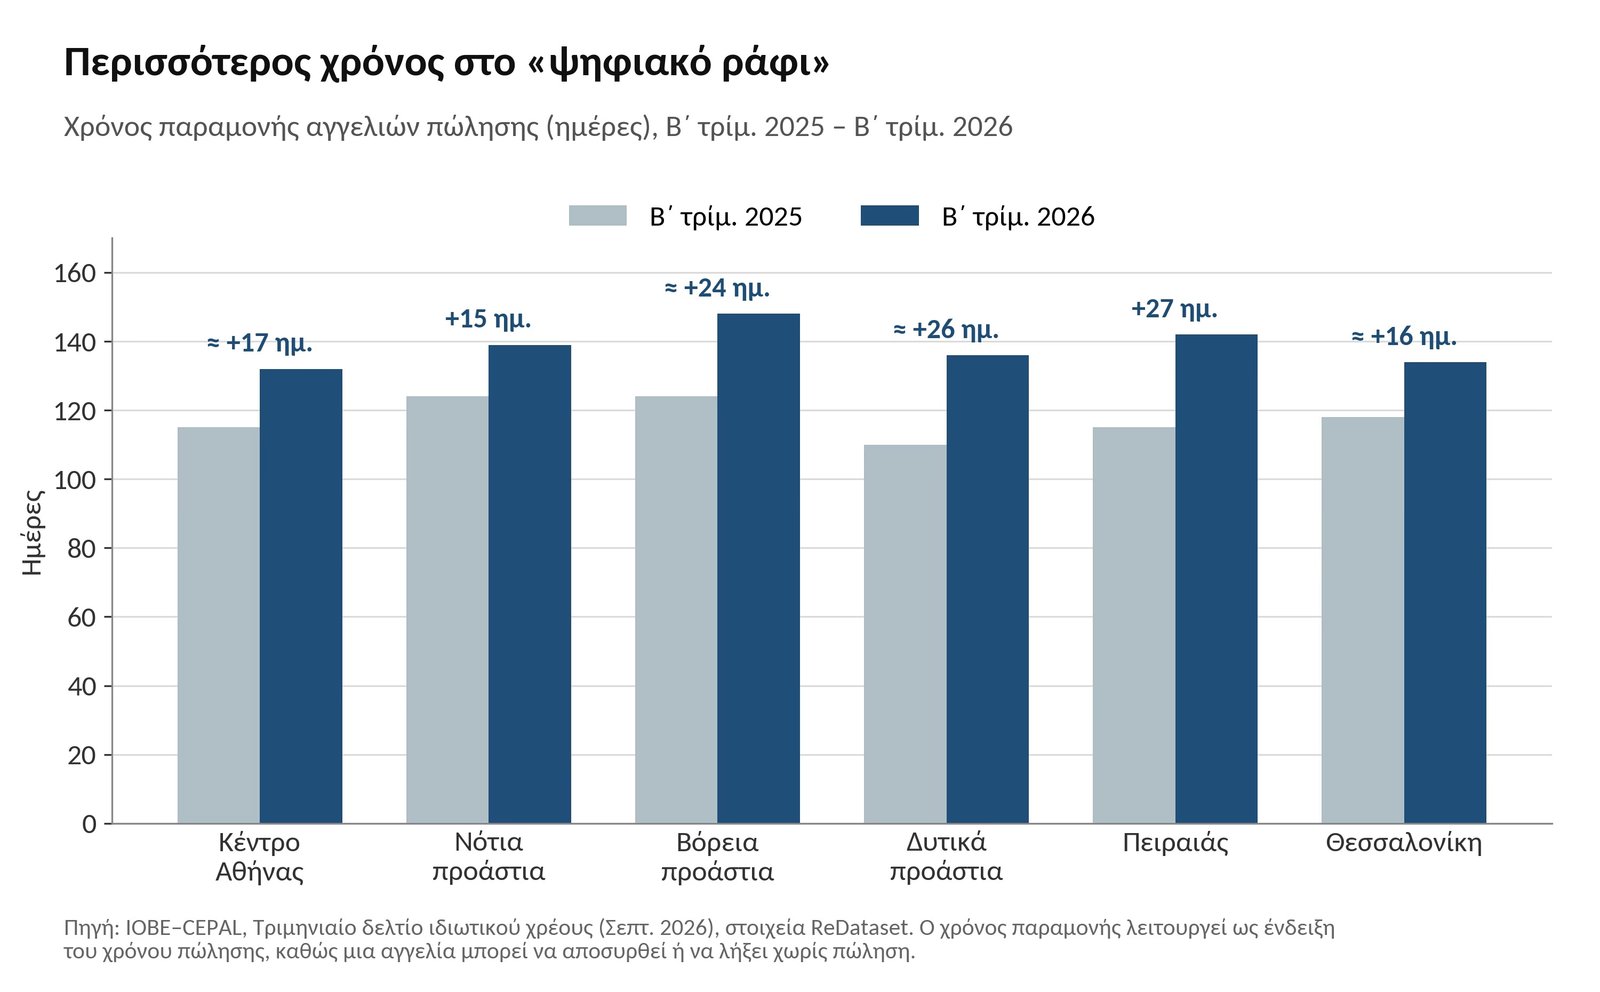
Ο χρόνος παραμονής των αγγελιών στις ψηφιακές πλατφόρμες αυξήθηκε σε όλες τις περιοχές, από 15 επιπλέον ημέρες στα νότια προάστια έως 27 στον Πειραιά. Στο κέντρο της Αθήνας μια αγγελία έμενε αναρτημένη περίπου 132 ημέρες, από 115 έναν χρόνο νωρίτερα, ενώ στα βόρεια προάστια ο χρόνος έφτασε περίπου τις 148 ημέρες, τον υψηλότερο μεταξύ των έξι περιοχών. Μία πιθανή εξήγηση είναι ότι αρκετοί πωλητές, παρότι η αγορά δεν ανταποκρίνεται στις τιμές που ζητούν, προτιμούν να περιμένουν μια καλύτερη προσφορά, αψηφώντας το «κάλλιο πέντε και στο χέρι παρά δέκα και καρτέρει».
Το δελτίο δεν εξετάζει τα κίνητρα των πωλητών και επισημαίνει ότι ο χρόνος παραμονής αποτελεί ένδειξη και όχι μέτρηση του χρόνου πώλησης, αφού μια αγγελία μπορεί να αποσυρθεί ή να λήξει χωρίς να πουληθεί το ακίνητο. Σημειώνει επίσης ότι, όσο οι αγγελίες μένουν περισσότερο στις πλατφόρμες, τόσο διογκώνεται μηχανικά και το απόθεμα των ενεργών αγγελιών.

Νεόδμητα στα προάστια, παλιό απόθεμα στο κέντρο
Η σύνθεση της νέας προσφοράς διαφέρει σημαντικά από περιοχή σε περιοχή. Στα νότια προάστια το 31% των ενεργών αγγελιών αφορά κατοικίες που χτίστηκαν την τελευταία δεκαετία και στα βόρεια το 25%, ενώ στο κέντρο της Αθήνας και στον Πειραιά τα ποσοστά περιορίζονται στο 10% και στο 11%. Εκεί η αύξηση της προσφοράς προέρχεται κυρίως από παλαιότερα ακίνητα και, ειδικά στο κέντρο, από κενά διαμερίσματα που επιστρέφουν στην αγορά κατοικίας. Στα νεόδμητα, οι ζητούμενες τιμές των διαμερισμάτων ενός υπνοδωματίου ήταν 4,7% έως 9,2% υψηλότερες από έναν χρόνο νωρίτερα, ξεπερνώντας κάθε άλλη κατηγορία μεγέθους.
Νέες άδειες για μεγαλύτερα έργα
Η κατασκευαστική δραστηριότητα δείχνει ότι η προσφορά θα συνεχίσει να διευρύνεται. Στο πεντάμηνο Ιανουαρίου–Μαΐου 2026, οι ιδιωτικές οικοδομικές άδειες αυξήθηκαν κατά περίπου 16% τόσο στην Αττική όσο και στην Κεντρική Μακεδονία, ενώ η αντίστοιχη επιφάνεια αυξήθηκε κατά 61% και 78%, γεγονός που παραπέμπει σε μεγαλύτερα έργα. Καθώς ο πληθυσμός και ο αριθμός των νοικοκυριών μειώνονται, το ΙΟΒΕ εκτιμά ότι η ξένη ζήτηση πιθανότατα επηρεάζει τη νέα οικοδομική δραστηριότητα. Πρόκειται για εκτίμηση και όχι για μετρημένη σχέση, ενώ οι ξένες άμεσες επενδύσεις σε ακίνητα διαμορφώθηκαν στα 0,5 δισ. ευρώ το α΄ τρίμηνο του 2026, αρκετά κάτω από την κορυφή του τέλους του 2024.
Οι προτάσεις του ΙΟΒΕ
Για να μετριαστεί η δυναμική των τιμών, το ΙΟΒΕ σημειώνει ότι η στεγαστική πολιτική θα μπορούσε να εστιάσει στην επέκταση της προσφοράς, ώστε αυτή να ανταποκρίνεται καλύτερα στη μεταβαλλόμενη ζήτηση. Η παρατήρηση εκ πρώτης όψεως προκαλεί απορία, αφού η προσφορά ήδη αυξάνεται. Το επίμαχο ζήτημα όμως δεν είναι μόνο πόσες κατοικίες βγαίνουν προς πώληση, αλλά και τι είδους, σε ποιες τιμές και σε ποια κοινωνικά και εισοδηματικά στρώματα απευθύνονται.
Σύμφωνα με τη Eurostat, η Ελλάδα εμφάνιζε το 2025 το υψηλότερο ποσοστό στεγαστικής υπερεπιβάρυνσης στην ΕΕ, με ένα στα τέσσερα νοικοκυριά να δαπανά πάνω από το 40% του εισοδήματός του για τη στέγαση. Παράλληλα η χώρα διαθέτει ένα πολύ μεγάλο απόθεμα κενών κατοικιών. Δεκάδες χιλιάδες από αυτά έχουν περάσει στα χέρια μεγάλων funds – servicers μέσω κατασχέσεων και «κάθονται», περιμένοντας την κατάλληλη στιγμή για να πέσουν στην αγορά κατοικίας. Εν τω μεταξύ τα ενοίκια παραμένουν στα ύψη και η στεγαστική κρίση οξύνεται, ιδίως για τα πιο ευάλωτα τμήματα του πληθυσμού. Πρόκειται για ένα εκρηκτικό μείγμα, στο οποίο οι στεγαστικές πολιτικές της κυβέρνησης δεν έχουν δώσει μέχρι σήμερα ουσιαστική λύση.

