
LAST INFORMATION 13:05
of Manos Hachladakis
At the pace of the international sell-off, the Athens market is swept away after a meeting of expanded losses yesterday mainly due to Coca Cola.
In particular, the General Index now negotiates at 2.555.3 units with -2.15% and high turnover at 120m euros, while 15.5 million pieces have been moved.
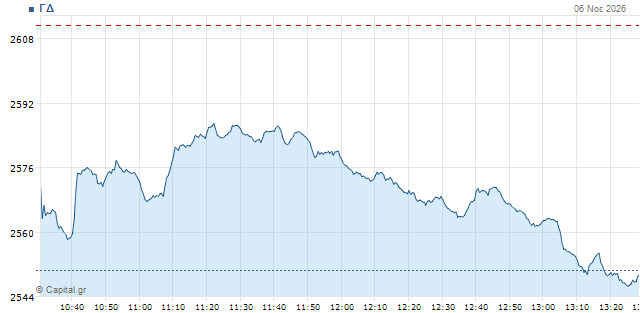
The banking index negotiates at 3,072 units with -2,1%, the FTSE of high capitalization at 6.549 singles with -2,1% and the FTSEM of the middle at 3.058 singles with -1,6%.
The Athens Avenue had a difficult meeting yesterday and returns to trade within an expanded negative external environment after the technological... massacre yesterday on Wall Street, whose tsunami of liquidations was moved this morning to Asia and now Europe.
Regarding the markets of the Old continent the horizon had begun to "darken" as early as yesterday afternoon after the intense downward opening of indicators in the US, however, within the border was another case, dictated mainly by -14% of the most heavy share in Euronext Athens.
In this respect, investors have shown to overreact in the news that Russia has proceeded to nationalise Japan Tobacco Internatiol, fearing that a small Russian brewery will also have a similar outcome. for Multon, subsidiary of Coca Cola HBC. However, in addition to the fact that the company was subsequently presented reassuring as to the possibility of changes in its operational status in Russia, the assessment of its activities in the country is estimated at 2.7 billion ECU. According to Eurobank Equities, i.e. the value of its title represents an amount of EUR 2.2 per share and certainly not the dive of almost EUR 10 made intra-sessions yesterday (high day at 60.4 and closing at 50.50).
From there on, in the international field, positions today are defined by the free fall made yesterday by Wall Street and especially its technological branch (Nasdaq 100 dip 6.4% on its worst day since 2000 of the pandemic), as in Korea (Kospi) and Japan (Nikkei) losses in the morning reached 6% and in the European dashboards exceed 1% shortly after opening.
Generally the mass technological unload is attributed to the prevalence of Democrats in Congress and concerns that they will put "frey" in the (rague) development of data centers, especially after and from some statements yesterday of their officials who showed in this direction, however the reaction to the market showed to be more technical in nature, since in their fundamentals American businesses and especially those of the wider ecosystem of artificial intelligence still show indicators of explosive growth.
At the same time we also have a strong quarter overall at corporate announcement level, as 82% of S&P 500 companies that have published results have exceeded analyst estimates of their profits per share (EPS) and 70% of the expectations for revenue.
Therefore, it is more likely that yesterday's movement in technology involved more general fears that have been expressed before (e.g. for leverage levels), with the dimensions it took to trigger possible and forced liquidations by important institutional investors, despite the fact that a mass shift is unfolding (from now on at least) outside the sector that will have a prolonged duration. Something that remains to be seen, of course, with the results announced by Nvidia (17 November) having, as usual, increased gravity.
Moves on the dashboard
Climate indicator is that after 3 hours of trading just 1 title in high and medium capitalization has a positive sign, the UAE and this with small profits of 0.9%.
In the 25th year Coca Cola continues to be under increased pressure, with 2.9% out of EUR 49.05, which further burdenes the DG's image.
Metlen.
The titles of the DTP, which first attempted to "defence", have now been carried away too.
Eurobank at 2.9%, the EIB at 2.4% and Alpha and Piraeus at 2.2%.
Similarly, Cyprus is retreating by 2.7% and Credia by 1.9%, while Optima is the only title in the 25th along with OTE that holds losses below 1%.
Corresponding is the image of the mid caps, where ABax retreats by more than 3% and PPAs, Sarantis, Intralot, Intacom and Ideal note losses that exceed 2%.
In the total tableau just 7 titles move up and 97 pitches.
The image internationally
Oil moves with marginal changes. Brent at $98.5 with +0.3% and American WTI at $90.9 with +0.4%.
However, European physics is declining to EUR 87.7 per day with - 3.2 per cent.
In stock, the contracts of the US market indices show a mood of moderate technological recovery after yesterday's sale.
Dow Jones' futures at -0.9%, S&P 500 at +0.3% and Nasdaq at +1,4%.
It is noted that at noon in Greece (15:30) the report on the US labour market is expected in October, from which analysts expect to show the creation of 59,000 to 65,000 new posts after the extremely low number of September 29,000.
In Europe, sellers have a clear lead since morning and are expanding it.
German DAX at -2.3%, British FTSE 100 at -2,2%, French CAC 40 at -1,8%, Italian FTSE MIB at -1,3%, Spanish IBEX at -1,2% and the pan-European high capitalization of Stoxx 50 at -1,6%.
In the bond market, changes in yields are limited. Ten-year US at 4.85%, German at 3.24%, French at 4.81% and Greek at 4.14%.
Finally, the metals note contained losses. Gold at $4.075 an ounce at minus 0.9% and silver at $51.9 at minus 0.9%.

