
of Manos Hachladakis
With the buyers "gasing" the Athens market held a general rise meeting, considerably expanding the highs of the year and 17 years and approaching another milestone.
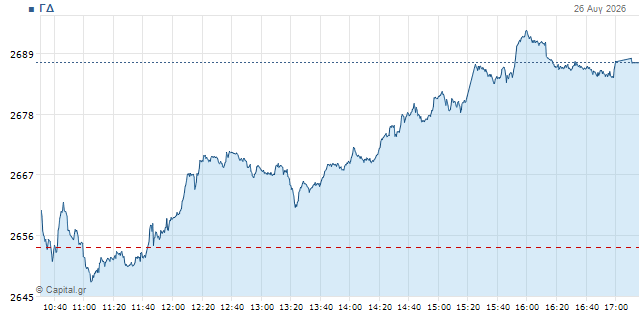
In particular, the General Index completed trade in 2,687,04 units with +1,26%, having been found intra-sessionally by 2.692.9 single (+1.49%).
The banking index was reinforced by 1,58% THE 3,148.5 units, the FTSE of high capitalisation against 1,29% THE 6,875.2 mon. and the mid-term FTSEM 0,95% THE 3,126.3 mon.
The turnover was increased in EUR 280,82 million (last night at 266.4 million) of which 38.8 million in 42 packages (8 in PPC for 11.6 million, 6 in Piraeus for 10.7 million, 4 in the EIB for 4 million, 2 in Eurobank for 2 million, 2 in Titan for 1.7 million, 2 in AKTOR for 1 million) with the volume of transactions in 35,07 million pieces.
More generally, the meeting today seemed to have three phases, as by about 12 there was some nervousness with alternating adjustments, but with banks rising paces the market has since initially stabilised to positive ground and when around 14:20 the DG broke through 2,670 units took off over and over 2,690 units.
In the positives of the day was that trading activity continued to increase paces and even more that there was a greater diffusion of liquidity in the lower layers, especially in the middle capitalization that yesterday remained virtually inactive.
From there on the picture probably confirms that larger portfolios had narrowed their movements in recent times, to an expected extent due to seasonality and possibly somewhat more with the background of wider uncertainty worldwide, but by improving the climate internationally they are rushing to take positions again.
In this regard, a guide to increased risk-taking internationally remains the double (and associated to a certain extent) deescalation of upside pressure on oil and government bond yields. With regard to American titles and especially long-term securities, although there is no marked decline in yields, data on swap rates and options suggest that Bessend intervention with the increase in purchases is already reflected on the market.
In macroeconomic developments, the US inflation figures PCE preferred Fed index (structured at 3.3%) showed that price pressures remain far from the bank's objective, as the analysts expected.
In this climate the eyes of the international investment community are now turning to the large established corporate event every quarter in recent years, the results of the company – the flag of the wider trade of artificial intelligence and by extension of global markets, Nvidia, after the closure of trades tonight on Wall Street.
Moves on the dashboard
A major protagonist of the day was PPC, which ejected at 23.7 euros with a 3.86% jump and the biggest turnover of the day at 37m euros, after +2.7% yesterday.
Banks started the meeting nervously, but along the way the buyers rose several paces.
Piraeus with 33.9 million at 10.34 euros with +2.38%, Alpha with 23.6 million at 4.65 with +1.97%, EIB with 23.9 million at 16.90 with +1.72% and Eurobank with 29.9 million at 4.62 with +1.03%.
Cyprus (31 million) was also strengthened by 1.1% to 10.61 euros, while Credia (2.8 million) remained unchanged and Optima (4 million) fell 0.25% marginally.
After PPC in 25aris, Titan (3.3 million) followed with a 2.99% jump to 53.35 euros, having from EYDAP (1.4 million) to 12.7 to +2.38%.
In addition, Coca Cola (31 million) gave the DG a boost with +1.3% at EUR 54.60, while more than 1% in high capitalisation was also noted by AKTOR (7 million) with +1.54%, GEK TERNA (11.9 million) with +1.34% and Aegean (1.9 million) with +1.33%.
Motor Oil continued to be at the heart of attention making the fourth biggest turnover of the day at 22.6m euros but with a corrective move at 58.80 euros with -0.93%, although it initially saw orders up to 61 in the aftermath of explosive sizes of EBIDTA over 1 billion in the semester.
Allwyn (8.7 million) was also moved to 14.45 to minus 0.76% in view of her own announcements tomorrow.
In mid caps IPTO made a 4.1% jump at 4.55 euros with a turnover of 4 million and Avax with 1.8 million discontinued a four-day drop with +2.97% at 3.47.
On the contrary, Alter Ego with 1.2 million retreated to 6.27 euros with -0.63%, PPA (384 km) to 40.30 to -1.47% and Furlis (244 km) to 4.29 to -0.8%.
In the lower layers SIDMA (144 km) continued its rally with a new +4,03% at 2,84 euros, Frigoflass (45 km) closed at +5,16% and CPI (33 km) at +7,8%.
Real Consulting with a turnover of 731 mm rose 3.75% and Performance (120 mm) was strengthened by 3.14%.
A total of 74 titles were completed with a positive sign and 49 with a negative (77 unchanged).
The image internationally
Oil prices continue to decline, though milder than in the morning.
Brent at $86.8 a barrel with minus 2% and American WTI at $80.8 with a minus 1.9%.
Similarly, European gas negotiates at EUR 64.6 per megawatt hour with -2.7 per cent.
In the shares Wall Street shows minor changes in the first phase, with several investors likely holding a waiting position ahead of Nvidia's announcements.
Dow Jones around the unchanged, S&P 500 at +0.1% and Nasdaq also without substantial change, in the first half of the hour.
In Europe indicators have now stabilised on positive soil. German DAX at +0.65%, French CAC 40 at +0.75%, British FTSE 100 at +0.3%, Italian FTSE MIB +0.7%, Spanish IBEX 35 at +0.5% and the pan-European high capitalization of Stoxx 50 at +0.65%.
In the bond market the yields have a slightly upward slope after a small retreat in the morning. The ten-year US at 4.66%, the German title at 3.21% and the French at 4.07%, with the Greek at 3.87%.
Finally, in metal, salesmen have a small lead. Gold around $4,670 with minus0.5% and silver at $68,3 with minus0.6%.

