
of Manos Hachladakis
Limital changes for the General Index but ejecting the trading activity had the last August meeting, with the implementation of the rebalancing of MSCI indicators and major protagonist Motor Oil.
In particular, the General Index was moved within a limited range of 20.8 units (high at 2.690.2 and low at 2.669.5) and ended in 2,677,26 mon. with a limit change -0,1%.
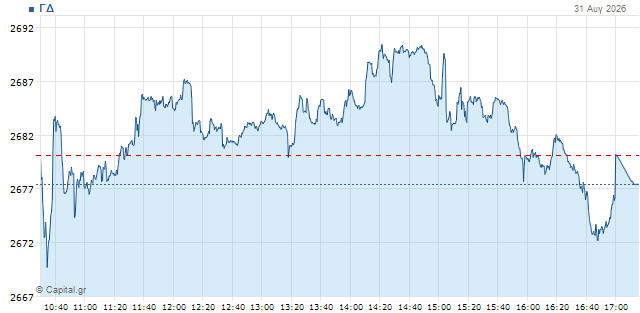
Banking index closed on 3.132,1 units substantially unchanged (resensitive + 0.01%), the FTSE of high capitalisation in 6,847,7 mon. with -0,1% and the mid-term FTSEM 3.131 unit. with +0,39%.
The turnover was fairly low during transactions (just at 149.3 million at 17:00 with the DG completely unchanged) but was ejected to EUR 802,94 million by applying the rebalancing of MSCI indicators.
The value of the (22) packages was EUR 37.1 million (1 in Motor Oil for EUR 24.1 million, 3 in Helleniq Energy for 1.7 million, 3 in Piraeus for 3.2 million, 2 in Eurobank for 2.7 million ) while the volume of transactions was set at 60.1 million pieces.
As a whole, the DG was assisted by 4,18% By completing five upward months, with DTP in +5,64%.
In today's meeting, in addition to rebalancing, this was of reduced interest, with extremely low tempo and selective moves suggesting a waiting attitude, while the revival of hostilities in the Middle East gave new impetus to oil prices by contemplating investors internationally.
In Athens attention focused mainly on Motor Oil, which monopolized the turnover and before the rebalancing which concerned it to a large extent as it reverted to MSCI Standard Greece, and from there on to the banks that showed sufficient volatility.
Another feature of the day was that in the whole dashboard the sellers kept a steady lead and quite enlarged in some phases, but it was not reflected in the variation of the DG due to the indicators of support received throughout the meeting.
Moves on the dashboard
Motor Oil had made mixed-value transactions of 25.9 million at 17:10 (+ 0.67% at 60.50 euros) and eventually its turnover was ejected to 344.1 million closing at 60.15 with a marginal change of + 0.08%.
Second in trade was GEK TERNA with 77.9 million and -0.77% at 46.64 euros.
Piraeus with 59.6 million closed at 10.28 euros with +0.78%, Eurobank with 58.6 million at 4.58 with -1.38%, EIB with 42.2 million at 16.88 with +0.15% and Alpha with 40.9 million at 4.57 with + 0.04%.
PPC made joint transactions of 41 million with +0.5% at 23.98 euros.
Allwyn with 29.3 million retreated to 13.50 with -2.32% and Jumbo with 20.5 million at 26 with -0.84%.
OTE with 13.6 million stayed at 19.80 and Helleniq Energy with 12.9 million recorded a slight rise of 0.26% to 15.51.
At the peak of FTSE Credia (8 million) jumped 3.2% to 1.02 euros, while EYDAP (1.8 million) was strengthened by 1.76%, Titan (2.4 million) by 1.68%, Optima (4.2 million) by 1.25% and Biocos (2.4 million) by 1.06%.
Beyond Allwyn and Eurobank no other title of high capitalization had losses of more than 1%, with Metlen (5.5 million) at -0.72% and AKTOR (4.2 million), Lamda (819 thousand) and ELHA (1.5 million) all around -0.8%.
In mid caps Kri Kri who enters Greece Small Cap made a turnover of 6 million with -2.16% at 31.70 euros (at 17:10 she had made 1 million with -0.77% at 32.15).
The UAE (195 km) rallied 5% at 8.38 euros and Alter Ego (860 km) followed close by + 3.2% at 6.43.
On the reverse, Furlis (415 km) retreated by 2.03% and ABax (534 km) by 1.44%.
In the lower layers EPAP (227 mm) recorded strong losses 3.56% at 4.60 euros and MIG (41 km) took a 5.2% dive.
A total of 57 titles were completed with a positive sign and 70 with a negative (80 unchanged).
The image internationally
Oil moves uphill again pressing $90 a barrel now, after the new ignition in the Middle East.
Brent at $90.9 with + 3.2% and American WTI at $86 with +3.1%.
Similarly, European gas is at 70 euros per megawatt hour with a 4.5% jump.
In shares, American indicators move downwards under the weight of energy prices, but with Wall Street heading towards closing an upward month (S&P 500 +3% before today's meeting).
Dow Jones in minus 0.65%, S&P 500 in -0.4% and Nasdaq in -0.3%, in the first half-hour.
Gradually red is growing in Europe as well. German DAX at -0.9%, French CAC 40 at +-0.2%, Italian FTSE MIB +0.2%, Spanish IBEX at -0.1% and the pan-European high capitalization of Stoxx 50 at -0.6%.
In the bond market returns are now being strengthened on both sides of the Atlantic. The ten-year US at 4.75%, the German title at 3.31% and the French at 4.16%, with the Greek at 3.99%.
Τέλος, πιέσεις δέχονται και τα μέταλλα. Ο χρυσός πέριξ των 4.480 δολαρίων με -1% και το ασήμι στα 66,24 δολ. με -0,9%.

